“Never make predictions,” advised baseball legend Casey Stengel. “Especially about the future.”
I share that view. Nevertheless, with next week’s so-called “Election Day” approaching, there’s uncertainty whether Democrats will regain control of the House and/or Senate.
Although election talk is loud, the reality of the economy speaks even louder. Politicians and commentators focus on party loyalty and personalities, creating much spectacle.
Meanwhile, everyday people face steep price shocks at gas stations and grocery stores, along with persistent inflation affecting many sectors.
No matter the election’s outcome, vehicles still require gasoline, trucks need diesel, and planes rely on jet fuel. Before fuel reaches consumers, refineries must process crude oil using specialized catalysts, electricity, heat, skilled labor, and ongoing maintenance. This highlights that any country aiming for strength and prosperity must command sufficient, reliable energy resources.
Today, let’s consider three key points (and later, four companies) investors should bear in mind during and after the election:
- First, the fuel shortage stems primarily from refining challenges, not just crude oil availability;
- Second, America’s push to rebuild industry favors firms connected to tangible assets and physical output;
- Third, U.S. military strength fundamentally depends on the nation’s energy and industrial capacity.
These principles hold true regardless of which party wins next week or controls Congress. Sure, politics can cause market swings, but the laws governing fuel, machinery, and logistics operate independently.
We Have Oil, but Refined Fuel Remains the Bottleneck
“Oil” is often used to mean energy in general, but that’s like saying the Army or Navy runs on iron ore alone—which is only true far upstream at iron mines. Real military capability depends on finished hardware powered by refined fuels.
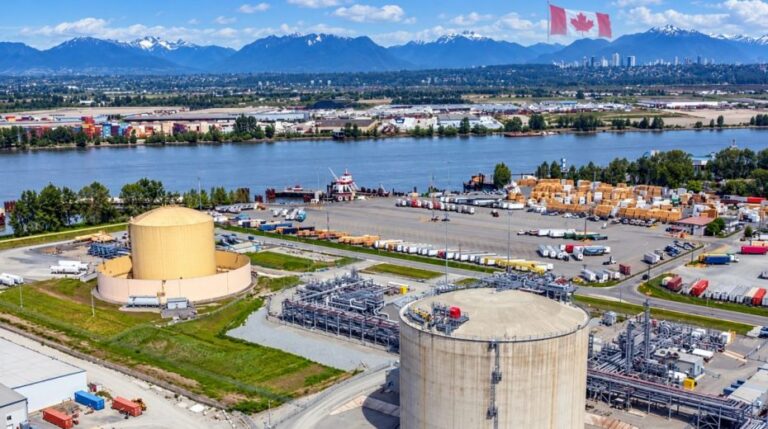
No one fills vehicles or aircraft with crude oil directly; they rely instead on gasoline, diesel, and jet fuel. Between the oil wells and fuel stations lies a complex, costly industrial system that heats, pressurizes, breaks down, purifies, and reassembles hydrocarbons into usable products. A vast logistics network also transports these fuels from one point to another.
While most people’s interaction with oil is through gasoline in cars, diesel is actually the lifeblood of the physical economy. It powers freight transportation, mining, agriculture, and construction. Jet fuel, chemically related to diesel, sustains both commercial airlines and military air forces.
These middle distillates—diesel and jet fuel—compete for refining capacity, which is limited. As we have explained previously, when refining capacity tightens, rising fuel prices ripple through the entire economy.
Thus, simply having access to crude oil does not ensure affordable fuels. Across the U.S. and many parts of the so-called “developed” world, significant refinery capacity has been shuttered, repurposed, or poorly maintained. Existing plants can operate hard but face physical constraints in equipment and maintenance.
While importing some diesel, for instance from Russia, might temporarily ease price spikes, it cannot fix the longstanding shortfall in refining infrastructure.
The pragmatic solution to fuel shortages doesn’t lie in mythical new refineries appearing overnight; that’s unrealistic. Instead, the approach is called “debottlenecking,” which means upgrading existing facilities—improving heat exchangers, pumps, catalysts, controls, maintenance—and selectively expanding or restarting idled units. These are unglamorous investments, but they reliably boost fuel output.
Investors should monitor refining profit margins, inventory levels, maintenance schedules, and regional transportation logistics, because America’s energy challenge extends beyond crude prices. Election promises may sway sentiment, but fuel flow depends ultimately on refinery throughput.
Reindustrialization Represents a Long-Term Strategy
For many years, the U.S. prioritized financial maneuvering over maintaining physical production capacity, allowing industry to move offshore, decay, or face prohibitive regulations. Business schools even developed programs centered on shutting down domestic production, outsourcing jobs, and relying on low-cost foreign labor, framing this as managerial achievement.
Whichever way the election turns, the next two years of President Trump’s potential second term will be a test of whether “reindustrialization” is genuine policy or just rhetoric.
The key questions are simple: Can projects secure permits and reliable power? Will infrastructure such as pipelines, railroads, ports, and energy transmission expand? Can education systems cultivate skilled workers? Can investments generate returns without getting bogged down in red tape?
Opportunities stretch beyond oil. New manufacturing calls for steel, copper, cement, chemicals, machine tools, transformers, gas turbines, electrical grids, and large amounts of electricity. Data centers may seem digital, but they are massive physical structures needing land, concrete, cooling water, continuous power, and robust transmission networks. AI may reside in the “cloud” (which isn’t actually sky-bound), but it still depends entirely on the power grid.
This calls for a fresh investment perspective. Investors should prioritize productive assets over mere narratives. Favor companies that control resources, reserves, extraction, processing systems, technical know-how, equipment, and logistics—assets that can’t be replicated or hacked through software updates.
Reindustrialization will produce winners, but it will also reveal shortages in energy, materials, labor, and effective execution.
Washington can help by reforming permitting, offering tax incentives, leveraging defense procurement, and using industrial development authorities. Still, laws of physics, chemistry, and engineering cannot be overturned by policy. Projects will demand time, billions in capital, and competent management. Markets will reward firms already possessing valuable infrastructure that can expand prudently.
In short, expect election-related volatility but focus on capital expenditures. Track investments flowing into pipelines, plants, power generation, and production.
Military Strength Reflects Industrial and Energy Might
The broader point is this: military power fundamentally derives from energy and industrial strength. A country transforms energy, raw materials, factories, labs, shipyards, refineries, and the electrical grid into combat-ready forces capable of deployment and sustained operations.
Without jet fuel, fighter jets are nothing but costly metal displays. Tanks without diesel become static targets. Missiles lacking electronics, specialty metals, and chemical propellants are useless. A navy without shipyards, spare parts, and trained personnel quickly degrades into a wasting asset.
Modern economies mask this military backbone behind a civilian façade. Ports, pipelines, rail yards, data centers, payment systems, and communications networks serve commerce during peace but transform into vital military logistics in times of crisis. They move fuel, handle intelligence, finance procurement, and keep supply lines open.
Conflicts in Ukraine and the Middle East highlight this sharply: destruction of refineries, power grids, ports, and transportation routes can degrade military effectiveness as much as frontline casualties. Efficiency measures like just-in-time inventory, cloud services consolidation, and lean supply chains save money until disruptions cause cascading failures.
National defense extends beyond the Pentagon’s budget. It encompasses spare transformers, resilient fuel reserves, redundant ports, domestic metallurgy, repair facilities, secure information, and surge manufacturing capability. Energy security is inseparable from defense strategy; it forms its foundation.
This explains why the election outcome matters. Political gridlock that stalls infrastructure, deters investment, or dismisses industrial projects as partisan (e.g., “a Trump Thing”) will manifest as higher prices, job losses, and strategic vulnerabilities. On the other hand, policies boosting reliable energy and industrial capacity enhance both economic prosperity and national deterrence.
Key Takeaways for Investors
Here are three central points to remember:
- One: The primary fuel risk lies downstream—in the conversion of crude oil into diesel, gasoline, and jet fuel.
- Two: Reindustrialization benefits firms focused on tangible assets, prudent capital deployment, and operational excellence.
- Three: National defense depends on energy, manufacturing, and logistics long before weapons reach the battlefield.
No matter what unfolds after Election Day, don’t mistake the uproar for the real story. We may witness protests, legal battles, political spectacle, and volatile markets—that’s merely noise.
The true underlying factor is whether the U.S. can produce energy, refine it efficiently, transport it, convert it into industrial output, and safeguard the systems enabling all of this.
Four Investment Ideas to Consider
Lastly, while Reckoning isn’t an investment newsletter or portfolio tracker, here are some companies worth noting regardless of political winds:
- Exxon Mobil (XOM): A large integrated energy firm with broad operations in production, refining, chemicals, and complex projects—well-positioned for a world where energy security yields premiums.
- Chevron (CVX): A high-quality global producer with resilient assets, financial strength, and deep operational experience, suited for ongoing oil and gas demand.
- Schlumberger/SLB (SLB): A top oilfield services and technology provider benefiting as producers invest more to develop tougher resources.
- Valero Energy (VLO): A leading independent refiner with direct exposure to the scarce capability that turns crude into the diesel, gasoline, and jet fuel vital to the economy.
None of these companies guarantee smooth profits—no investment does—but they represent capable operators tied to the real economy of molecules, machinery, and throughput. As the world rediscovers the value of hard assets, investing in these assets remains relatively affordable.
That concludes today’s discussion. Thank you for reading and subscribing.
About the Author