Gold, Credit, Character… and the AI Economy
“Money is gold, and nothing else,” banker J.P. Morgan declared during his 1912 testimony before Congress.
Morgan made this statement following the Panic of 1907, a period when credit collapsed globally and the U.S. economy plunged into turmoil.
By 1912, lawmakers were immersed in discussions about preventing future financial crashes. Consequently, they called upon Morgan to offer insight on money and the issue of “trusts.”
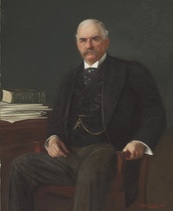
Portrait of J.P. Morgan by Fedor Encke. Credit: National Portrait Gallery, Smithsonian Institution
Morgan’s clear distinction between gold and credit was fundamental, pun intended. Gold signifies value that has already been extracted and refined. As a tangible asset, gold’s worth does not rely on future actions by anyone else. Conversely, credit represents a claim on value yet to materialize, often based on anticipated performance.
Simply put, gold is tangible and real, whereas credit is a promise—an important one—but its reliability hinges on the borrower’s ability to honor it. Morgan emphasized during his 1912 testimony, “The first thing (about extending credit) is character, before money or anything else. Money cannot buy it.”
This emphasis on character complements another of Morgan’s famous remarks: “It is always best to have no money in your account. Then you are forced to use your brain.”
A promise gains credibility only when the person behind it is trustworthy and possesses the ability to produce and deliver the promised value. For instance, a farmer is granted credit because of expertise in cultivating crops.
This circles back to Morgan’s assertion that “money is gold,” and how credit fuels production by bringing future value into the present. The tie between gold and credit lies in character and knowledge. Character ensures a promise is believable; knowledge, through skill and productive ability, enables fulfillment.
As for knowledge, it is neither currency nor a promise but underpins the credibility of a promise. Historically, this form of knowledge was rare, residing in the minds of experienced, trained workers—like butchers, bakers, and candlestick makers.
Enter writer Emad Mostaque. His 2025 book, The Last Economy: A Guide to the Age of Intelligent Economics, investigates how the traditional scarcity of knowledge might now be coming to an end.
When Knowledge Becomes Capital
Mostaque is highly analytical, and this precision is valuable. Yet, in some ways, he echoes the “quants” whose reliance on mathematical models contributed to the excesses behind the 2008 financial crisis.
Though Mostaque never directly references J.P. Morgan, he intriguingly picks up from where the veteran New York banker left off and takes new ideas further.
While Morgan held that gold was existing value and credit advanced future value grounded in promises and character, Mostaque investigates how knowledge is swiftly evolving into a crucial factor that enhances these promises’ reliability.
Traditionally, capacity to deliver results was limited because it was linked to knowledge held by skilled individuals. Artificial intelligence (AI) has altered this dynamic by converting increasingly large shares of knowledge and judgment into endlessly repeatable software.
Put differently, AI doesn’t eliminate value; it shifts its location.
With the ability to copy vast data sets, analyses, and decisions at extremely low marginal cost, the premium on human knowledge or skills decreases. For example, legal software can now instantly perform tasks that once required significant time from human researchers.
AI increasingly places more value on capital that orchestrates intelligence, applies it productively, and translates outputs into goods, services, and revenue. Mostaque terms this the “intelligence inversion” central to The Last Economy.
According to Mostaque, traditional economic institutions were designed to allocate limited human expertise and judgment. But as such cognition becomes abundant and scalable, the foundation of many professions and industries is transforming.
Put plainly, many established jobs and ways of earning income are being disrupted, with AI often cited as the catalyst behind layoffs and hiring slowdowns.
With midterm elections nearing, AI’s political implications are gaining attention. While voters will hear discussions about AI’s impact on productivity, harder issues concern how jobs and wages will fare when businesses can achieve more with fewer workers.
Further questions arise: When intelligence is no longer scarce, how will economies assess value? And who benefits from this shift?
Seven Lies Behind the Intelligence Inversion
Mostaque argues that today’s economic framework is based on distributing rare resources, with competent skill and human judgment historically being the scarcest. AI transforms this by embedding much of decision-making directly into software, lowering marginal costs.
Seen through the scarcity lens, AI abundance may appear like systemic breakdown: many entry-level jobs and billable tasks vanish, along with revenue streams in diverse sectors.
Mostaque identifies seven “fatal lies” underpinning this system:
- Scarcity is fundamental
- Human labor has inherent economic value
- Reward follows contribution
- Growth means health
- Markets naturally produce efficient outcomes
- Technology creates more jobs than it destroys
- Human intelligence will remain economically indispensable.
One might debate these points, but they neatly summarize core assumptions behind labor markets, corporate strategy, and policy today.
When widespread AI cognition becomes available, wages and GDP growth might decline even as real productive power grows. The benefits will flow primarily to those who own the capital enabling AI’s broad deployment.
Where Marx Runs Out of Road
Mostaque’s perspective sharply diverges from Marx’s labor theory of value, which remains influential in some academic and political circles.
Marx connected a product’s value to the socially necessary labor invested and viewed profit mainly as a claim on workers’ surplus value—a theory rooted in the industrial 19th century, where physical toil dominated production.
Looking forward, AI models can absorb cumulative past labor—research, coding, engineering—and reproduce work repeatedly with minimal additional human input.
This means AI provides value repeatedly, while labor per unit nears zero. Established measures such as price, utility, and human effort no longer align as they once did.
Nor does the so-called “surplus” of productivity vanish, and exploitative dynamics remain possible. But scarcity shifts: it is no longer the raw human labor hours that matter, but control over the systems capable of performing these tasks repeatedly at scale.
So who controls these systems? Sorry, Karl Marx, but it’s owners of capital—those possessing data centers, semiconductor supplies, and reliable energy sources. In other words, those holding the economic levers between abundant digital knowledge and its practical output.
Thus, Mostaque’s inversion does not imply a classless society. On the contrary, it might intensify capitalism’s concentration, where intelligence is cheap at usage points, but the physical and financial infrastructure holders reap the majority of returns.
Gold Versus Credit Versus Knowledge
This brings us back to J.P. Morgan’s contrast of gold and credit.
Within Morgan’s framework, AI knowledge is neither cash nor credit, and lacks the “character” component. Due to AI’s minimal marginal costs, it isn’t a final settlement asset. Still, AI is a transformative production tool that broadens capacity to back credit while concentrating profits among owners of its physical infrastructure and energy.
Gold—as true “money”—lies outside the realm of AI. It neither predicts future output nor depends on someone’s integrity to maintain, say, power grids.
Gold retains its value without dependency on external promises, while credit constitutes commitments supported by character and ability to deliver future goods or services.
Although AI lowers production costs, it does not guarantee that promises will be fulfilled. In fact, cheaper intelligence might encourage more credit issuance based on anticipated productivity.
If those returns fail to materialize or concentrate too narrowly, credit obligations increase while the capacity to redeem them weakens. In such circumstances, gold’s role as a stable asset beyond the credit network becomes more vital—simply put, gold safeguards wealth across time.
Meanwhile, GDP and price indexes reflect only fragments of economic well-being. As many Americans can attest, a nation’s asset markets may thrive while infrastructure, manufacturing, and workforce skills deteriorate.
With AI adoption growing in the U.S. and globally, routine mental labor faces downward price pressure, whereas ownership over critical physical chokepoints gains value. Companies might accomplish more with leaner teams, resulting in fewer hires and less training of future experts—a challenge looming ahead.
Currently, nations with reliable power and manufacturing capabilities will have an edge over those that simply import intelligence.
The AI Economy Runs on Copper
Beyond owning gold, how should one position for this emerging landscape? Start with the understanding that cheap intelligence still requires energy—it’s not free.
AI systems operate nonstop on massive electricity supply.
The International Energy Agency anticipates global data-center power demand will nearly double by 2030, with AI-centric facilities driving much of the growth.
Power generation alone isn’t sufficient. Electricity must be delivered through extensive transmission networks, heavily reliant on copper. Building a single new transmission line demands physical metals, hardware, and construction—not something achievable with mere digital commands.
Moreover, this entire infrastructure requires design, permits, financing, manufacturing, and hands-on installation by skilled workers. AI may assist, but real people do real jobs. (Pro tip: strive to be THAT professional.)
Hence, Mostaque’s vision of abundant intelligence fundamentally depends on a foundation of talented individuals and tangible resources.
Invest in Durable Value
The takeaway is not to simply “buy AI.” Many of the valuable assets lie upstream from sectors where AI disrupts labor.
Take copper for example. While AI moves at software speed, copper mines take years to establish—permitting, raising capital, and construction precede production.
Beware: valuations may outpace cash flow, regulatory delays can occur, and consumers might resist paying for private data-center infrastructure.
A couple of companies worth watching:
Freeport-McMoRan (FCX), a U.S. and global diversified copper producer with market capitalization near $107 billion, also operating significant gold and molybdenum assets.
And Enphase Energy (ENPH), a U.S.-based energy tech firm valued around $4.6 billion, developing power electronics and advancing its IQ Solid-State Transformer platform tailored for AI data centers.
These aren’t formal recommendations but companies I track with expectations of sustained performance.
Asking the Right Questions
Mostaque’s The Last Economy is sharp, unconventional, technical, and thought-provoking. It raises essential inquiries like: As AI becomes ubiquitous, who controls the scarce resources that convert knowledge into reliable action and lasting gains?
Of course, J.P. Morgan provided the foundational monetary axiom long ago: Gold is money; credit is a promise backed by character and competence.
Looking ahead, whatever AI’s ultimate impact, behind every shining promise of software-enabled abundance lies a hard-edged, physical supply chain. Fuel, metals, copper wiring, transformers, chips, and trained professionals must all perform before promises are fulfilled.
That’s all for now. Thank you for subscribing and reading.
About the Author