The election results in Brazil were not what we anticipated.
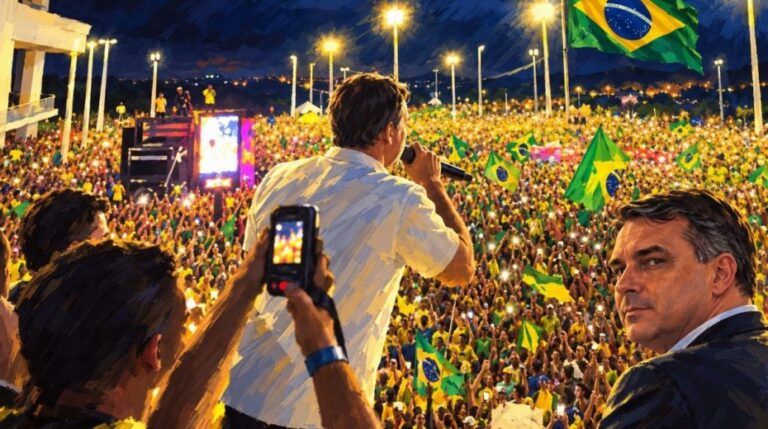
Lula, the 80-year-old socialist, secured victory in the presidential runoff, marking his fourth term leading the nation.
Just last week, prediction markets favored the right-wing contender, Flavio Bolsonaro, with an 81% chance of winning.
On October 5th, when Bolsonaro appeared poised to take the presidency, our preferred Brazilian ETF (EWZ) surged 13% within a single day.
Now, with socialism set to dominate for the next four years, we must rethink if Brazil remains a viable investment destination.
Stocks + Currency Plummet
Brazilian equities experienced broad declines today. The largest Brazil ETF (EWZ) dropped a staggering 21% as of 1:00 pm ET.
Petrobras (PBR, PBR.A), which has been a top performer for us this year, slid 15% during the session.
The Brazilian real depreciated by roughly 12%. This currency drop intensified the plunge in Brazilian shares, as foreign investors face amplified losses when domestic currency weakens against their home currency.
Nonetheless, I remain optimistic about Brazil. Since our initial February 2025 coverage, EWZ is still up 43% with dividends reinvested.
Likewise, Petrobras has gained 102% (including reinvested dividends) since our first May 12th analysis.
Political developments in South America clearly influence market returns, but this selloff seems exaggerated.
Socialist Concerns vs. Capitalist Optimism
Investors had hoped that a conservative leader would tighten deficit spending, deregulate the economy, and attract foreign investment.
That strategy is now off the table. Still, I intend to keep holding EWZ and other Brazilian assets, reinvesting dividends and riding out the volatility.
Petrobras remains a major holding in my portfolio, and I have no plans to liquidate it. Should that change, I’ll inform you.
Here’s why Lula doesn’t overly concern me. Despite his current term, Brazil has yet to experience economic collapse. Admittedly, Bolsonaro would have been more investor-friendly.
However, Lula’s track record since January 2023 includes notable reforms at Petrobras.
His administration redirected Petrobras to allocate more capital towards new oil exploration and production, reducing dividend payouts from roughly 60% to 45% of free cash flow.
The impact wasn’t entirely negative. Thanks to increased investment, Petrobras’ oil output has surged. Since Lula resumed office, production has risen by 27%, outperforming all other major producers. Substantial investments in Brazil’s rich pre-salt offshore reserves are paying dividends.
Thus, although Lula adjusted Petrobras’ policies, the company is producing oil at record levels and remains highly cash generative, with an average cost of about $35 per barrel.
The real concern for investors is a harsher form of government interference. Should oil prices stay high, Brazil might compel Petrobras to sell fuel at a loss domestically.
Between 2011 and 2014, the government imposed such controls, damaging confidence in Petrobras and Brazil’s stock market for years afterward.
That experience was a costly lesson. The market stagnated for over a decade following those actions. I doubt the government will repeat that mistake.
Even after today’s selloff, Brazil’s stock market ranks among the best performers globally over the last two years. I don’t believe Lula would sabotage the country’s economic revival.
Nevertheless, political risk remains a factor, as it does everywhere—including in the U.S.
Recurring Patterns
French economist Frederic Bastiat famously observed, “The state is the great fictitious entity by which everyone seeks to live at the expense of everyone else.”
Though penned in 1848, these words resonate strongly today, particularly in Brazil, where Lula’s promises for expanded benefits helped secure his win.
As the U.S. heads toward midterm elections, it confronts its own political challenges. A rising socialist-leaning Democratic party threatens to control Congress.
If that happens, the S&P 500 might not plunge 21% in a day like Brazil’s market, but a significant sell-off is likely.
Such a shift would signal a move toward more socialism in America, marked by higher taxes, wealth redistribution, increased censorship and regulation, relentless immigration, and initiatives like Green New Scam 3.0. They might also attempt Supreme Court expansion populated by neoliberals. I detailed these risks in President AOC’s First Term.
The U.S. is no longer shielded from political turbulence once thought unique to emerging markets. We could be facing our own “mini-Brazil” scenario soon.
That said, I’m holding my Brazilian shares for the long haul. Purchasing quality companies at roughly 9x earnings with attractive yields generally pays off over time.
My strategy remains unchanged: maintain holdings, reinvest dividends for about five more years, wait for significant valuation improvements, and then sell once prices rise considerably.
Of course, if circumstances alter, you’ll be the first to hear.
About the Author